
 AI Summary
Post Office Senior Citizen Saving Scheme (SCSS) is a government-backed savings scheme that gives senior citizens a higher interest rate than most bank fixed deposits and also helps them save income tax. The scheme offers 8.2% interest per annum for the October to December 2026 quarter, and the interest is credited every quarter.
SCSS is a central government scheme operated through post offices and authorised banks. Investment in this scheme qualifies for tax deduction under Section 80C of the Income Tax Act, up to ₹1.5 lakh a year. The account matures after 5 years and the maximum deposit limit is ₹30 lakh.
Interest is paid on the first working day of April, July, October and January every year. Maturity period (lock-in period) is 5 years. After maturity the account can be extended in 3-year blocks as per India Post rules.
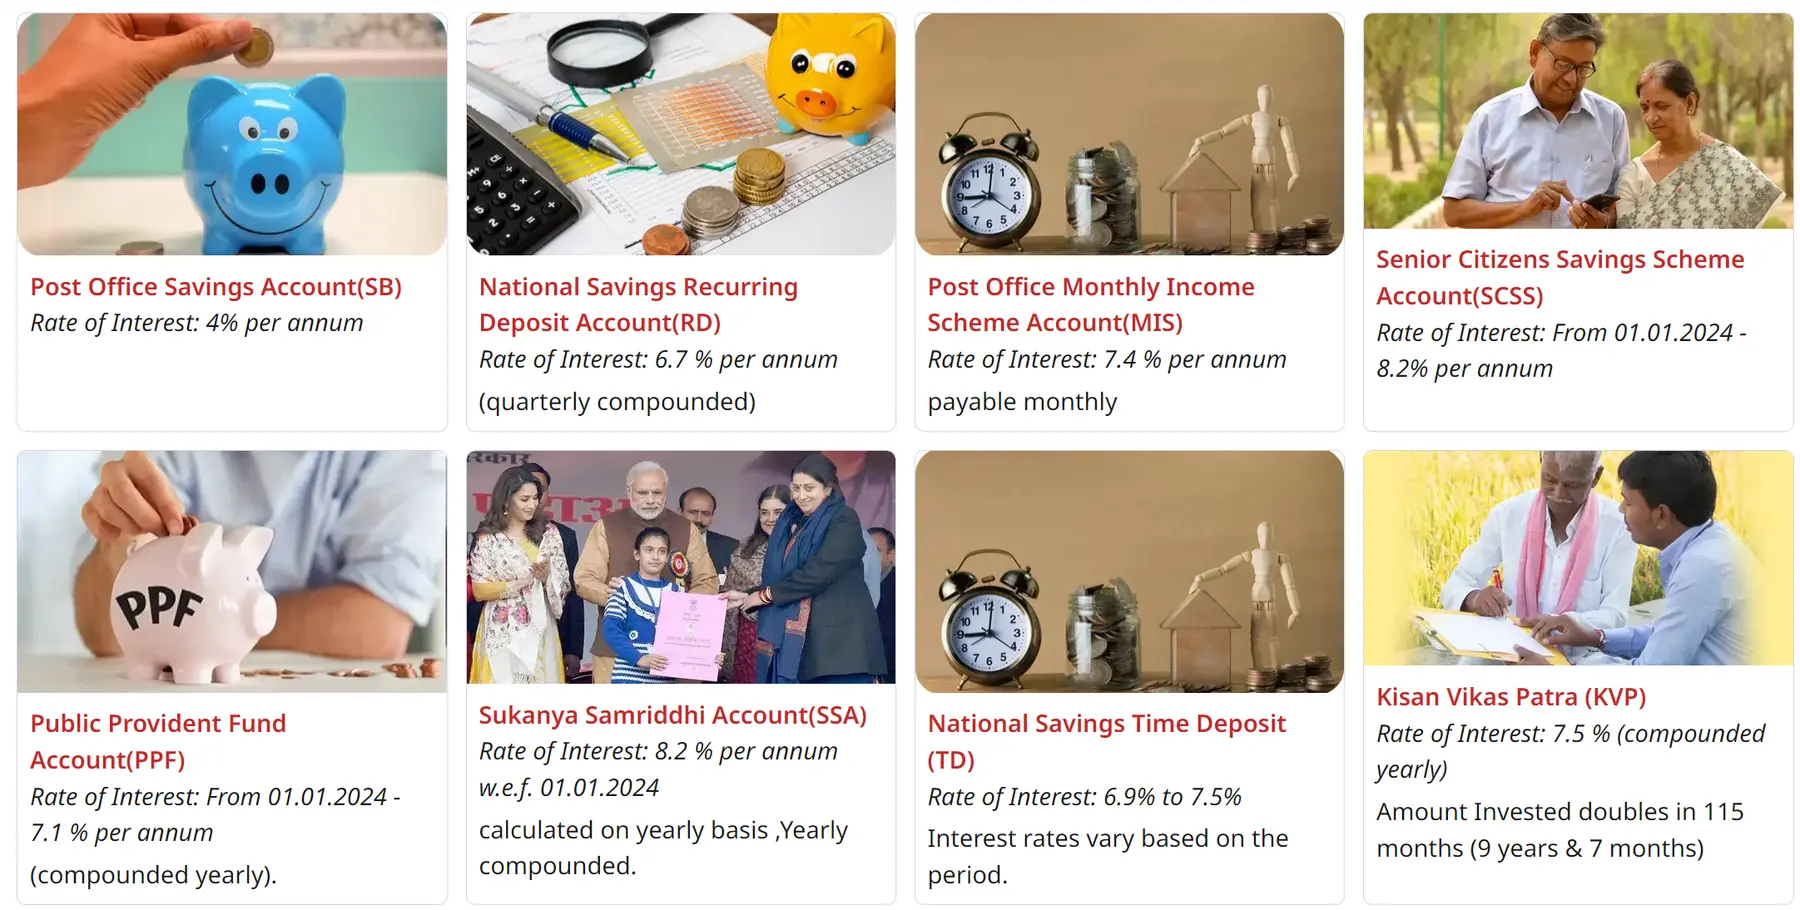
SCSS sits at the top of the small savings rate table, at par with Sukanya Samriddhi Yojana (SSY) and higher than National Saving Certificate (NSC), Public Provident Fund (PPF), Kisan Vikas Patra (KVP), Recurring Deposit - RD Account, Post Office Savings Account, Time Deposit Account (TD) and Monthly Income Scheme (MIS). For an easy comparison, check the post office scheme comparison guide.
Senior Citizen Saving Scheme Interest Rates
Central government reviews small savings rates every quarter. SCSS rate stands at 8.2% per annum for the October to December 2026 quarter. Finance Ministry kept it unchanged in the review on 30 September 2026, and the rate has not moved since April 2023. PPF is at 7.1%, NSC is at 7.7%, and the other post office rates also stay the same for this quarter.
Post Office Interest Rates Table (October to December 2026)
| Post Office Savings Scheme | Interest Rate |
|---|---|
| National Savings Certificate (NSC) | 7.7% compounded p.a. but payable at maturity |
| Public Provident Fund (PPF) | 7.1% compounded yearly |
| Kisan Vikas Patra (KVP) | 7.5% compounded yearly |
| Senior Citizen Savings Scheme (SCSS) | 8.2% p.a.; interest paid quarterly on 1st working day of Apr/Jul/Oct/Jan |
| Post Office Recurring Deposit Account (RD) | 6.7% p.a. compounded quarterly |
| Time Deposit Account (TD) | 6.9% (1 year), 7.0% (2 year), 7.1% (3 year), 7.5% (5 year) p.a. calculated quarterly |
| Sukanya Samriddhi Yojana (SSY) | 8.2% p.a. compounded annually |
| Post Office Monthly Income Scheme (MIS) | 7.4% per year, payable monthly |
| Post Office Savings Bank Account | 4% p.a. |
Notes: KVP at 7.5% doubles the money in about 115 months (9 years 7 months). SSY at 8.2% compounds yearly. TD slabs of 1, 2, 3 and 5 years earn 6.9%, 7.0%, 7.1% and 7.5% p.a. respectively as per India Post.
SCSS interest is more than what most bank FDs pay today. FD interest is usually credited yearly, whereas SCSS credits interest every quarter on the first working day of April, July, October and January.
SCSS interest is taxable. TDS may be deducted if total interest in a financial year crosses ₹1 lakh for senior citizens. Anyone whose total income is below the taxable limit can submit Form 15H / 15G to get interest without TDS deduction. Deposits still qualify for Section 80C benefit. Check the latest details on the India Post savings schemes page.
Senior Citizen Saving Scheme Account Opening & Eligibility
SCSS account can be opened in any post office across India. It can also be opened in nationalised and private banks. There is no fully online account opening route, so the applicant or a family member has to visit the branch with PAN, Aadhaar, age proof and retirement benefit documents where applicable.
For deposits below ₹1 lakh, cash payment is allowed. Amounts above ₹1 lakh must be paid by cheque. Individuals fill application Form A along with pay-in slip Form D. The following categories of people can open an SCSS account:
- Any individual aged 60 years or above on the date of opening the account.
- Retired civilian employees aged 55 to 60, provided the investment is made within 1 month of receiving retirement benefits.
- Retired defence personnel aged 50 to 60, provided the investment is made within 1 month of receiving retirement benefits.
- Account can be opened singly or jointly with spouse only.
- The whole deposit in a joint account belongs to the first holder.
SCSS account can also be opened through banks. For State Bank of India, download the SBI SCSS account opening form.
SCSS New Rules from 1 July 2026
Premature closure rules for SCSS were updated from 1 July 2026 under the amended Senior Citizens Savings Scheme Rules, 2019. Here is how they work:
- Closing the account within 1 year of opening: no interest is paid, and any interest already credited is recovered by the post office or bank.
- Closing the account between 1 and 2 years: 1.5% of the deposit is deducted as penalty.
- Closing the account after 2 years: 1% of the deposit is deducted as penalty.
TDS on SCSS interest applies when total interest in a financial year crosses ₹1 lakh for senior citizens. This higher limit has been in force since 1 April 2025.
On maturity, the account can be extended in blocks of 3 years. The extension request must be made within 1 year of maturity, and the extended deposit earns the interest rate prevailing on the date of maturity. Fresh deposits are not allowed in an extended account.
Deposits above ₹30 lakh are refunded immediately. Until the refund is made, the extra amount earns only the normal savings account interest.
SCSS Account Opening Form PDF
Download the below post office account opening form which can be used to open an SCSS account as well as a normal savings account, RD, TD, MIS, PPF, SSA, KVP or NSC account.
Senior Citizen Saving Scheme - Nomination Facility
Single account, or joint account with spouse only, is allowed. Age of the first applicant is considered for eligibility. Nomination can be added at the time of opening or any time later by submitting Form C. If the account holder dies and the spouse is the joint holder or sole nominee, the account can continue till maturity when the spouse is eligible.
Senior Citizens Savings Scheme - Maximum / Minimum Amount
Only one deposit is allowed in an account, in multiples of ₹1000. Minimum deposit is ₹1000. Maximum deposit across all SCSS accounts is ₹30 lakh or the retirement benefits received, whichever is lower.
Check Investment / Lock In / Risk of Other Post Office Savings Scheme
People can compare all post office schemes on maturity period, minimum and maximum amounts, and risk factors. All are government-backed, so they are risk-free in principal terms. TD premature closure and other rules are as per India Post and notified guidelines.
FAQ's
What is the current SCSS interest rate in 2026?
SCSS pays 8.2% per annum for the October to December 2026 quarter. Interest is credited every quarter on the first working day of April, July, October and January.
Can the SCSS account be closed before maturity?
Yes, but penalty rules apply. Closing within 1 year means no interest and recovery of interest already paid. Closing between 1 and 2 years attracts a 1.5% penalty, and closing after 2 years attracts a 1% penalty.
Is SCSS interest taxable?
Yes, SCSS interest is fully taxable. The deposit qualifies for Section 80C deduction up to ₹1.5 lakh under the old tax regime. TDS applies when interest crosses ₹1 lakh in a financial year for senior citizens.
Can the SCSS account be extended after 5 years?
Yes, the account can be extended in blocks of 3 years. The request must be made within 1 year of maturity, and the extended deposit earns the rate prevailing on the date of maturity.
Thanks for your post. What will happen to my Scss if bank goes bankrupt or shuts down.
Is there safety for senior citizens in case bank shuts down
Hi,
Do SCSS at post office attract TDS.......Please clarify
TIA
Senior citizens already have a SCSS FOR 15 lacs . In the new SCSS 2023 scheme how can he open another account for 15 lacs as ₹30 lacs is allowed
If I deposit an amount of 5.00 Lacs @ 8.2% and after June'23 if interest rate either come down or increase, is there any effect on my deposited interest rate i.e. deposited money interest rate either come down or increase?